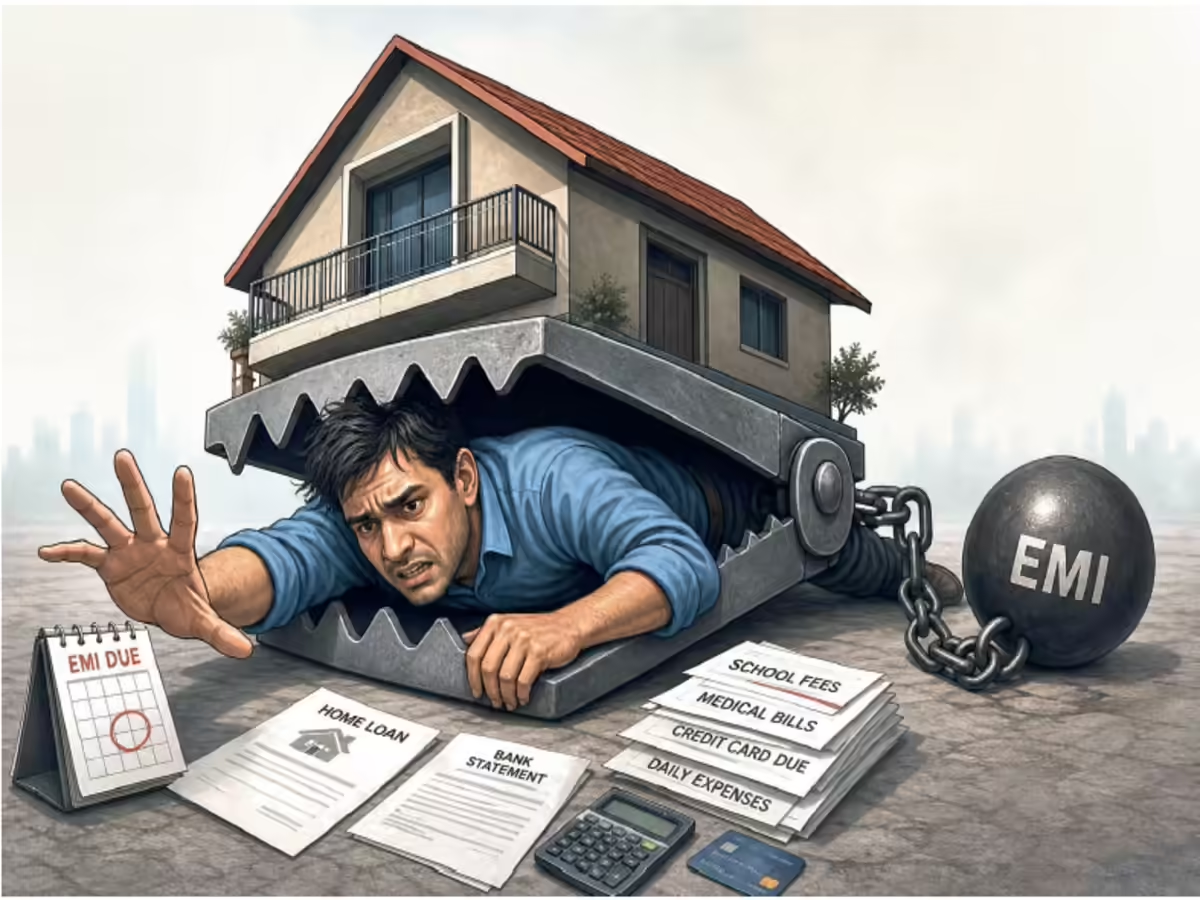
Buying a home is often seen as one of the biggest financial milestones in life. For many people, a higher salary also means they can consider a bigger house and take on a larger home loan. But there is a point where a home loan can start affecting almost every other part of a household's finances. A Gurgaon couple recently found themselves facing that exact choice while considering a property worth Rs 2 crore.The couple, who earn Rs 3 lakh every month, were looking at an EMI of around Rs 1.5 lakh. Instead of going ahead with the purchase, they decided to drop the plan. CA Nitin Kaushik highlighted the decision in a post on X, pointing out why the couple may have avoided a financial situation that could have put considerable pressure on their monthly income.Rs 1.5 lakh EMI on Rs 3 lakh incomeThe biggest issue was the size of the EMI compared with the couple's income. A monthly payment of Rs 1.5 lakh would have taken up half of their combined monthly earnings.As Kaushik explained in his X post, “₹1.5 lakh EMI means 50% of their monthly income going into the house.”That would leave the couple with another Rs 1.5 lakh for all their other expenses and financial commitments. A home loan, however, is not the only regular expense a household has to deal with. Groceries, travel, insurance, investments, family responsibilities and unexpected expenses can all add to the monthly outgo.The concern, therefore, was not simply whether the couple could technically pay the EMI. It was whether they wanted such a large part of their income committed to the house every month.The cost of buying a house is more than the EMIA large home loan can look manageable when the focus is only on the monthly repayment. But household finances can become difficult when several expenses arrive at the same time.Kaushik pointed to this wider issue while discussing the couple's decision. “And that’s before groceries, parents, travel, insurance, investments, emergencies and everything else life throws at you.”This is where the Gurgaon couple's decision becomes relevant for other homebuyers as well. A salary may make a particular property affordable on paper, but that does not necessarily mean taking the loan is the right financial choice.— Finance_Bareek (@Finance_Bareek) Rising property prices can create pressureKaushik also connected the couple's decision to a larger trend in household finances. According to his post, property prices have been rising faster than household incomes, while household debt has also been increasing.This can create a difficult situation for buyers who feel they need to purchase immediately because property prices could rise further. The fear of missing out on a property can sometimes push buyers towards loans that leave little room in their monthly budgets.Kaushik questioned that approach, writing, “So buy now, prices will only go up isn’t always good advice.”Saying no can also be a financial decisionThe couple's decision does not necessarily mean they cannot afford to buy a home. It means they chose not to make a Rs 1.5 lakh monthly commitment on a Rs 3 lakh income.Kaushik summed up the broader lesson from the example: “Sometimes the smartest property decision is simply: I can buy it. But I don’t want my entire life to revolve around paying for it.”For prospective homebuyers, the example shows why the size of the EMI is only one part of the decision. The more important question can be whether the loan still leaves enough money for regular expenses, savings, investments and unexpected needs after the monthly payment is made.
Couple earning Rs 3 lakh per month reject Rs 1.5 lakh EMI: How they avoided a home loan trap, CA explains the math
A Gurgaon couple earning Rs 3 lakh a month decided against buying a Rs 2 crore home that would have required an EMI of around Rs 1.5 lakh. CA Nitin Kaushik highlighted the decision on X, pointing out that the EMI would consume half of their monthly income, leaving less room for everyday expenses, family responsibilities, investments and emergencies.
590 words~3 min read